
Dealer group directory
Browse individual company profiles and explore other dealer groups.
Explore Dealer group directoryExplore ten of the largest U.S. dealer groups by rooftop count, with maps of their franchise locations, company profiles, and a look at their geographic footprint across the country.
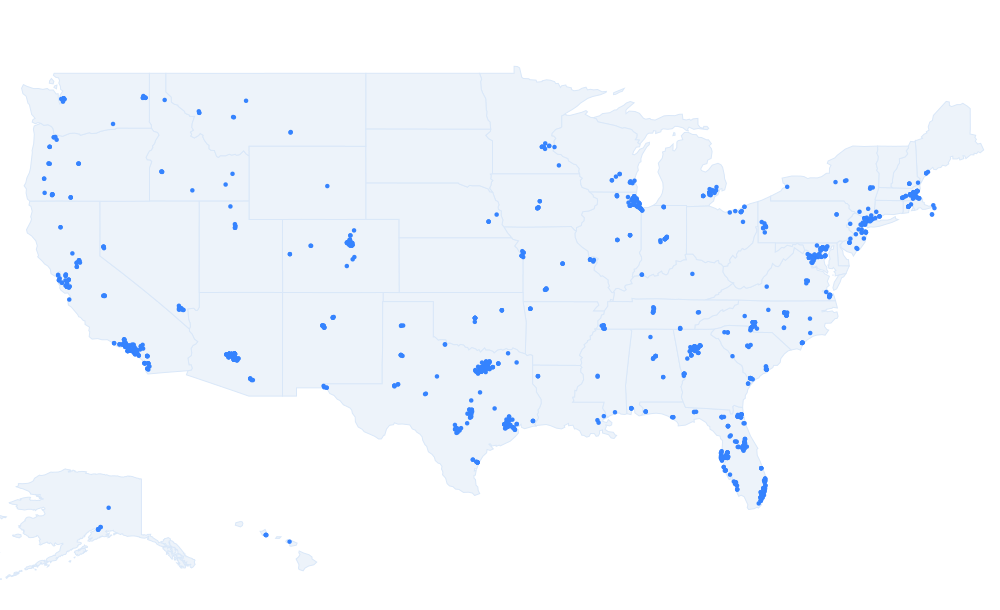
Ten leading dealer groups in this U.S. rooftop dataset.
Mapped franchise locations across the country.
See where each group operates and how they compare.
Select a group, view its footprint, and open the details.
Observed U.S. franchise addresses · Source updated July 9, 2026 · Counting methodology
Lithia & Driveway, AutoNation, Asbury, Group 1, Penske, Sonic, Hendrick, Berkshire Hathaway Automotive, Ed Napleton, and Morgan are the ten groups shown in this U.S. franchise-rooftop dataset. Their maps show how national networks and regional operators differ in geographic reach. There is no single ranking that answers every version of “largest dealer group.” Revenue measures the size of a business, unit sales measure vehicles sold, and rooftop counts measure physical locations. A nationwide car dealership group can also operate under local names that do not match its parent company. Use the maps for location coverage and the revenue comparison below for financial scale.
A dealer group owns or operates multiple dealerships. A franchise is a manufacturer authorization; a rooftop is a distinct dealership street address. Several franchises can share one rooftop. These counts cover active U.S. franchise dealership addresses in our MarketCheck records, last updated July 9, 2026.
| Dealer group | Rank | Observed U.S. rooftops | Ownership |
|---|---|---|---|
| Lithia & Driveway | 1 | 290 | Public · LAD |
| AutoNation | 2 | 248 | Public · AN |
| Asbury Automotive Group | 3 | 166 | Public · ABG |
| Group 1 Automotive | 4 | 142 | Public · GPI |
| Penske Automotive Group | 5 | 126 | Public · PAG |
| Sonic Automotive | 6 | 115 | Public · SAH |
| Hendrick Automotive Group | 7 | 95 | Privately held |
| Berkshire Hathaway Automotive | 8 | 87 | Berkshire Hathaway subsidiary |
| Ed Napleton Automotive Group | 9 | 84 | Privately held |
| Morgan Auto Group | 10 | 71 | Privately held |
One Chrysler-Plymouth store in Southern Oregon became a dealership network stretching across the country, including Alaska and Hawaii. Lithia started in 1946; today, its footprint puts it at the top of this list. The group also owns Driveway, its online car-buying business. That combination of local dealerships and online retail helps explain why Lithia's reach is much bigger than any single name on a showroom sign.
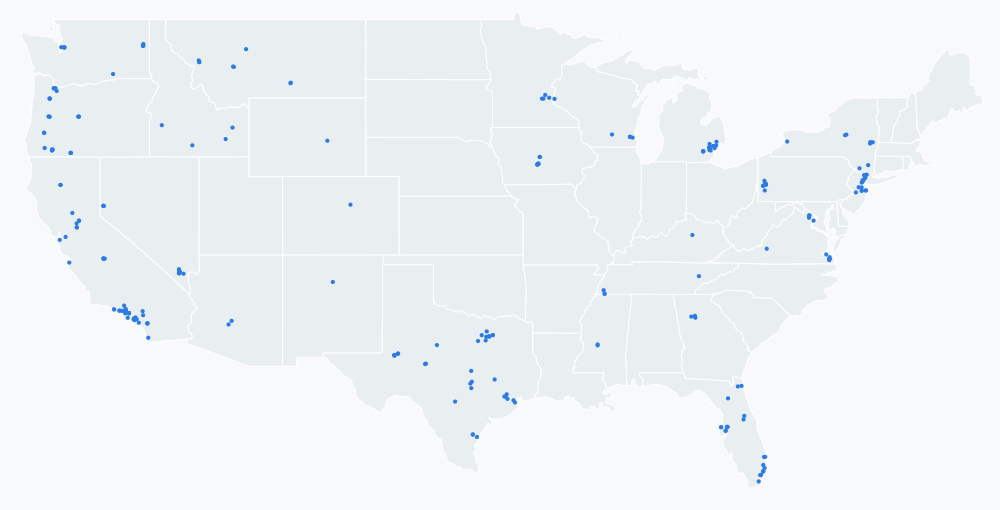
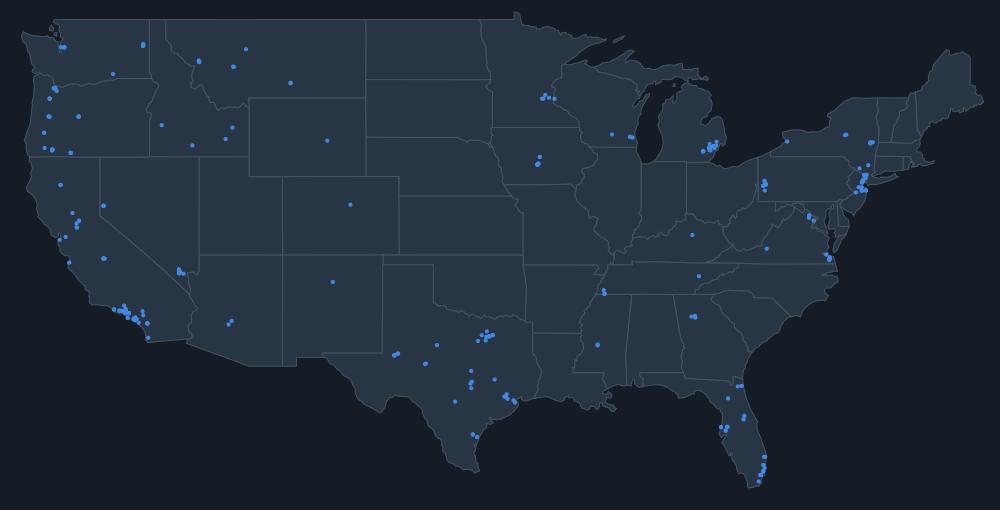
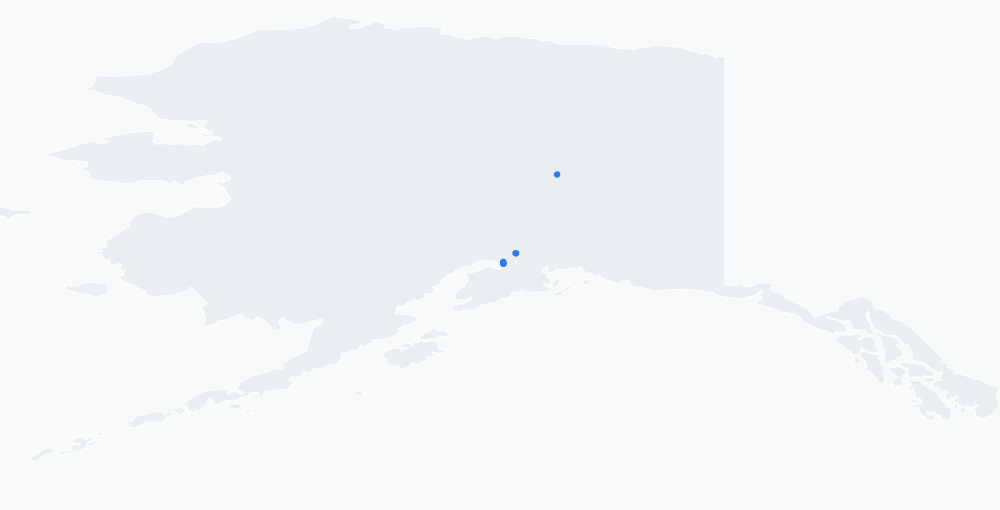
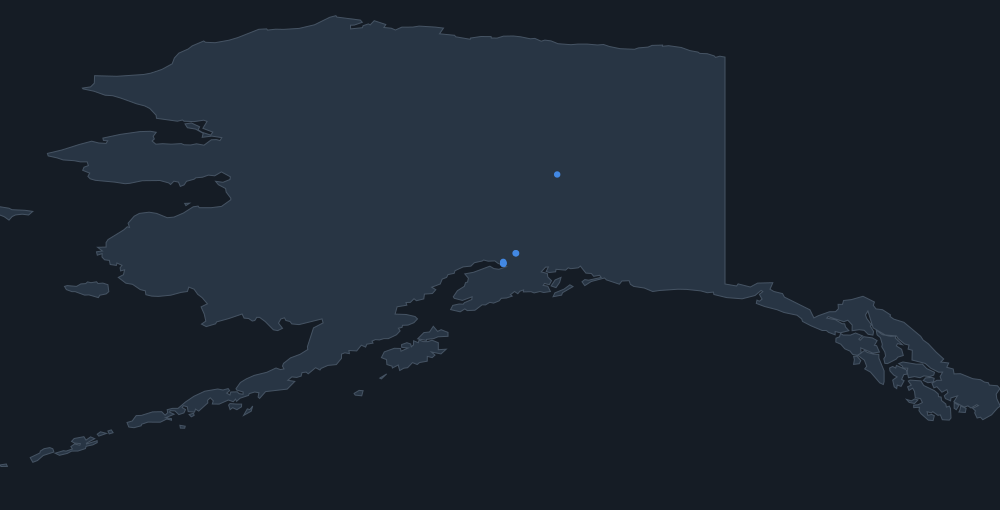 Alaska: 8
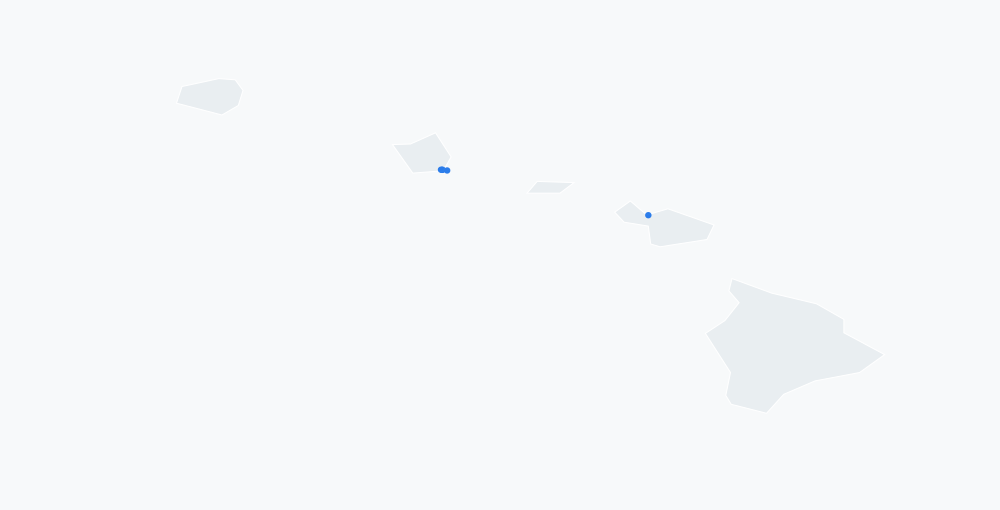
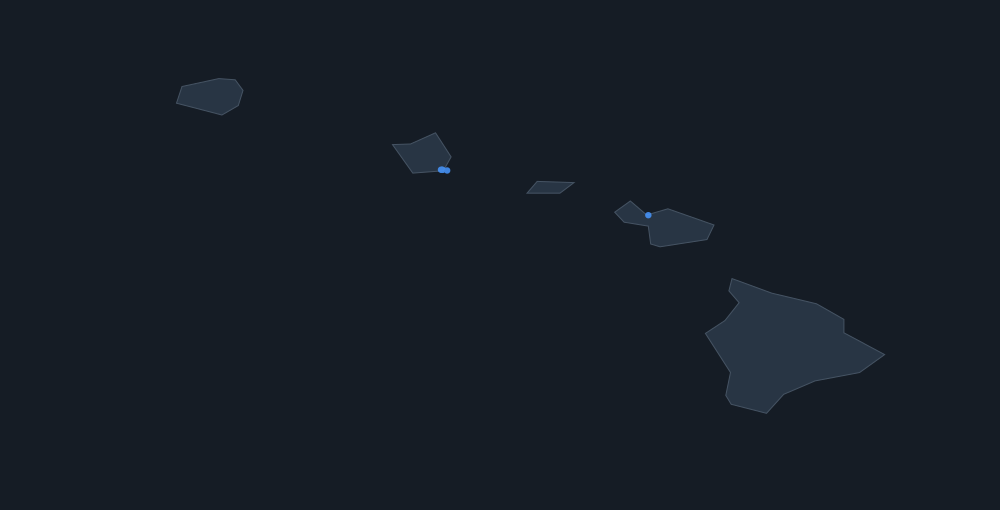 Hawaii: 5
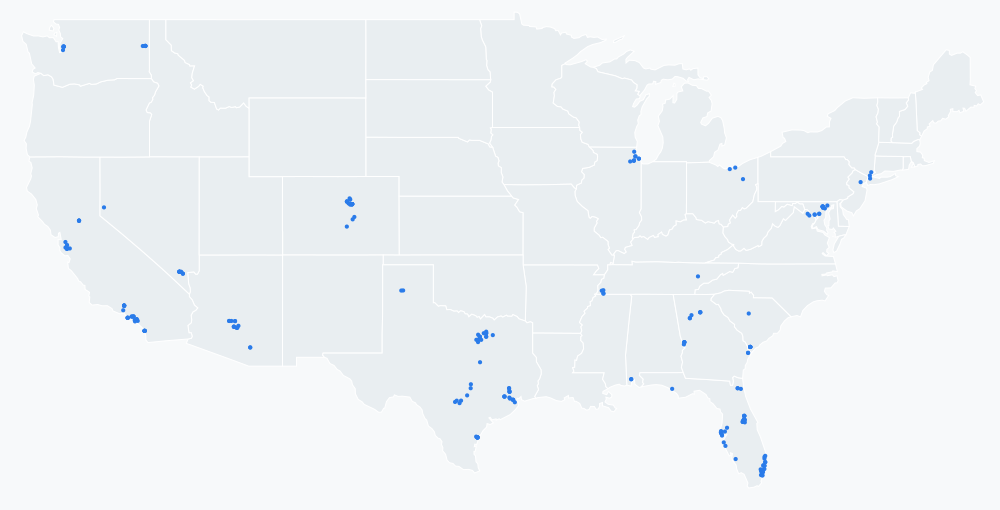
AutoNation puts a familiar retail name on dealerships selling many different vehicle brands. Its network spans 17 states on this map, connecting hundreds of local sales and service operations under one company. There is another identity running through the business: DRV PNK, AutoNation's cancer-support initiative. It's a distinctive part of a company whose presence extends well beyond the showroom.
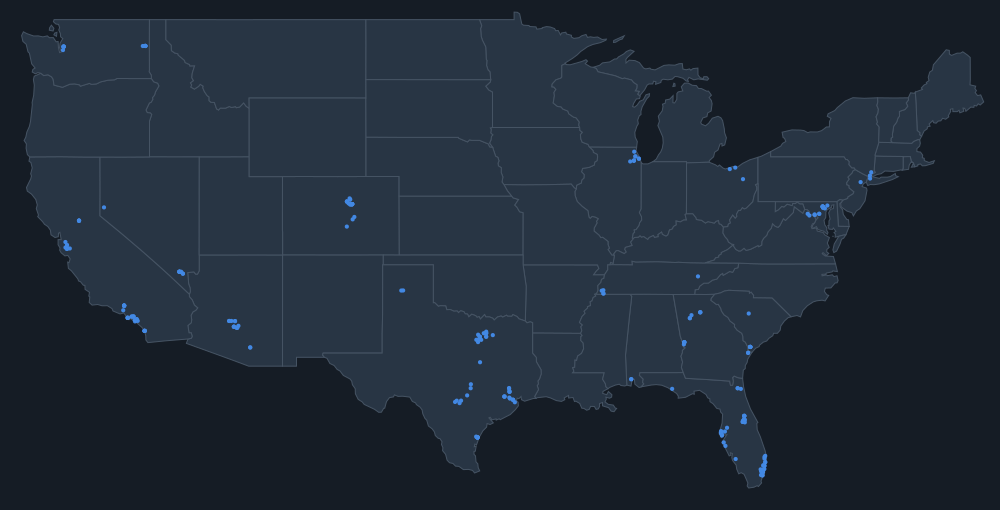
You may know Asbury through the dealership names it owns: Larry H. Miller, Herb Chambers, Park Place, and Coggin are all part of its family of brands. The local name on the building can hide the scale of the company behind it. Asbury also operates Clicklane, its online buying platform. Its story brings together established regional dealership businesses and a shared way to shop online.
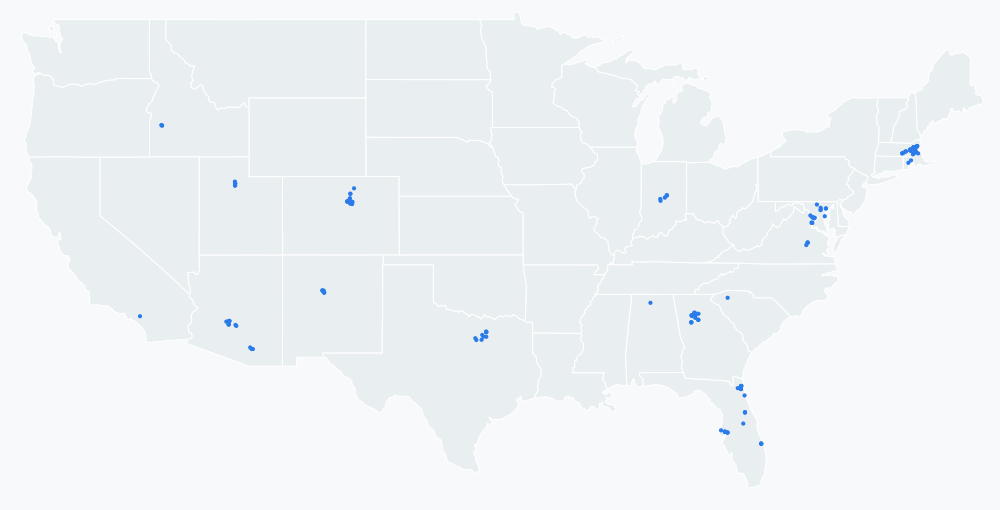
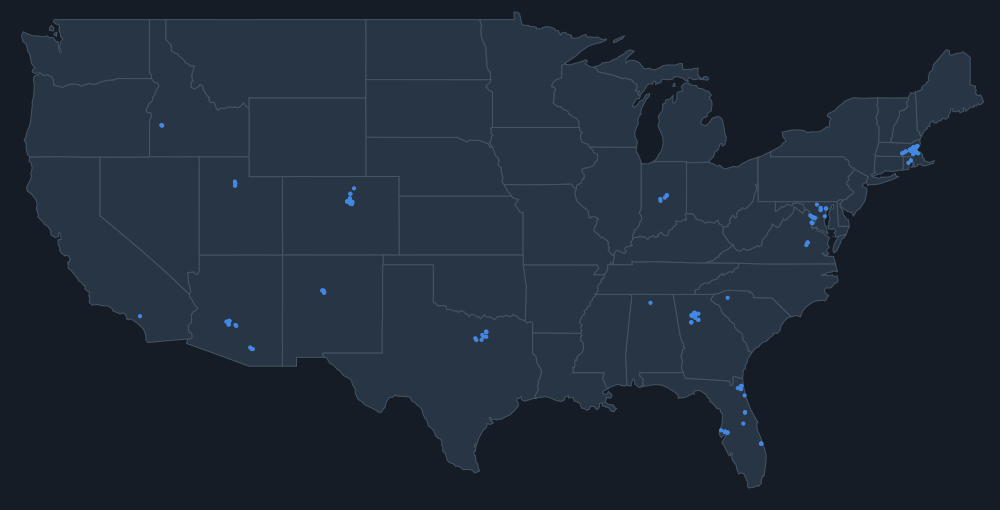
Houston-based Group 1 is the company behind local names including Ira, Bob Howard, and Gene Messer. Its U.S. dealership map reaches from Texas and the Gulf Coast to New England. The business continues after a vehicle leaves the lot: Group 1 sells parts, services vehicles, and operates collision centers. Its AcceleRide platform connects that physical dealership network with online vehicle shopping.
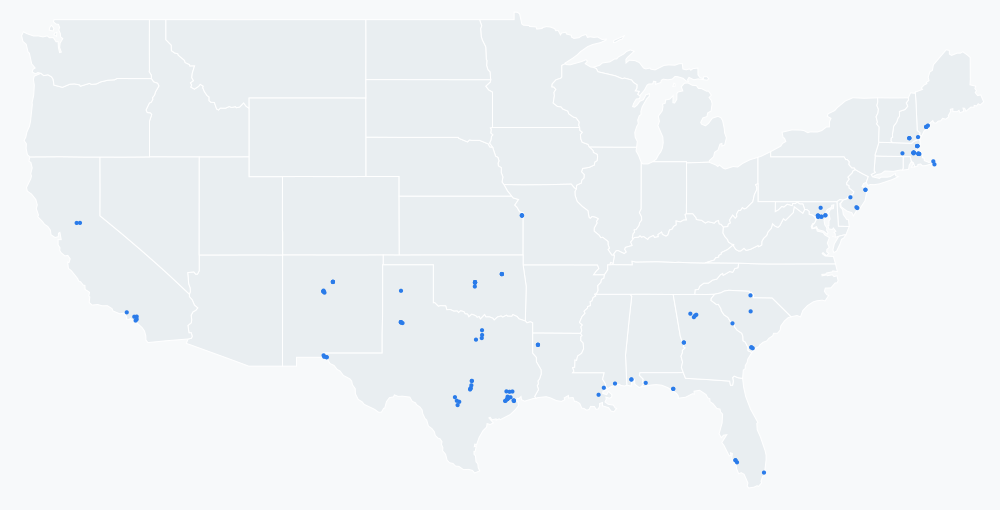
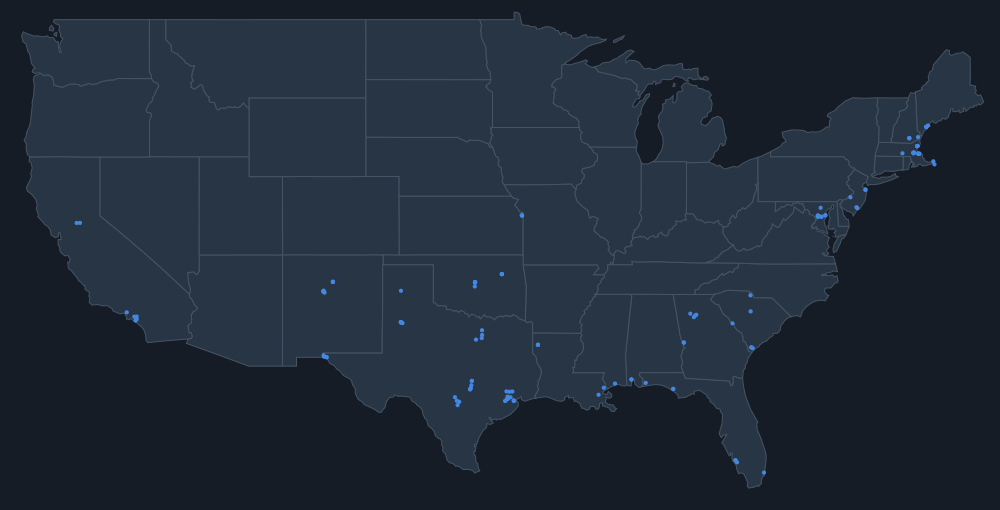
Penske's U.S. dealerships are one part of a much wider transportation business. The group also operates internationally and has a commercial-truck retail business alongside its passenger-car dealerships. That makes Penske an interesting name to follow beyond the auto mall. The map here focuses on its U.S. franchise dealership locations; its broader business reaches into other countries and vehicle categories.
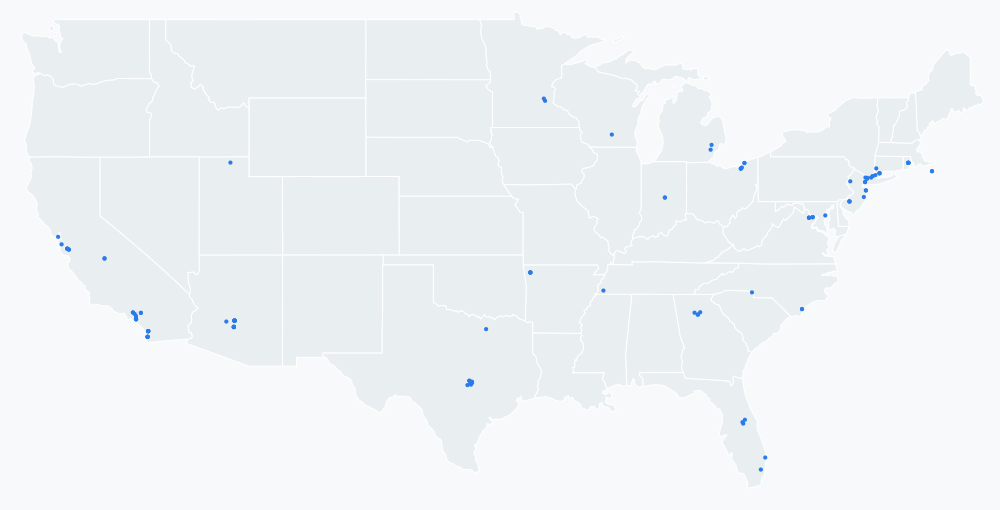
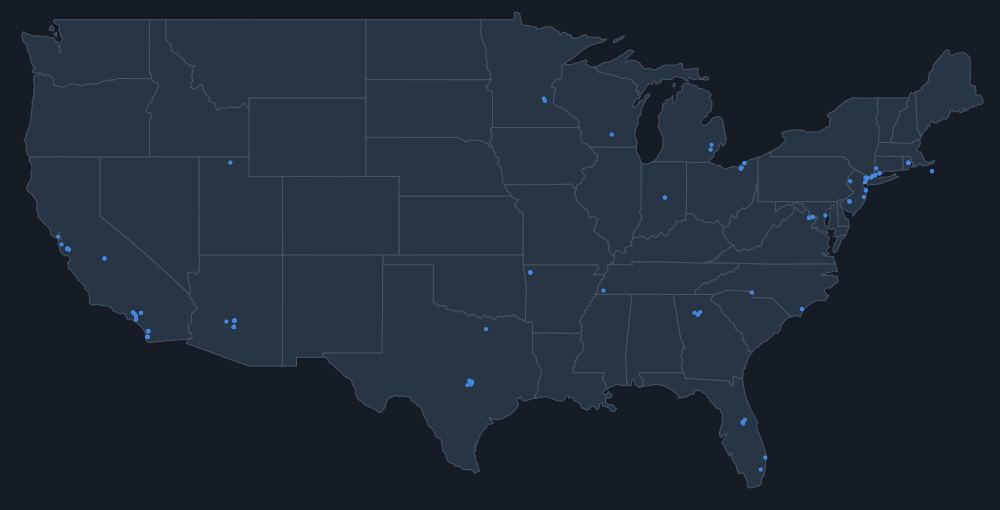
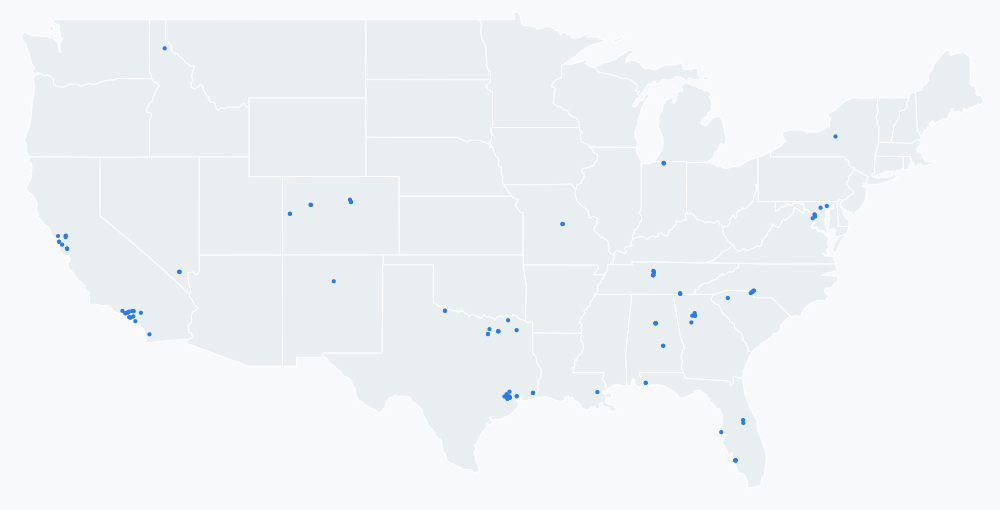
Sonic has motorsports in its family history. Founder Bruton Smith also founded Speedway Motorsports, and launched Sonic Automotive in 1997. The dealership business went public that same year. From those beginnings, Sonic grew into a network that stretches across the country. Its map brings together dealerships across 18 states, from California to the East Coast.
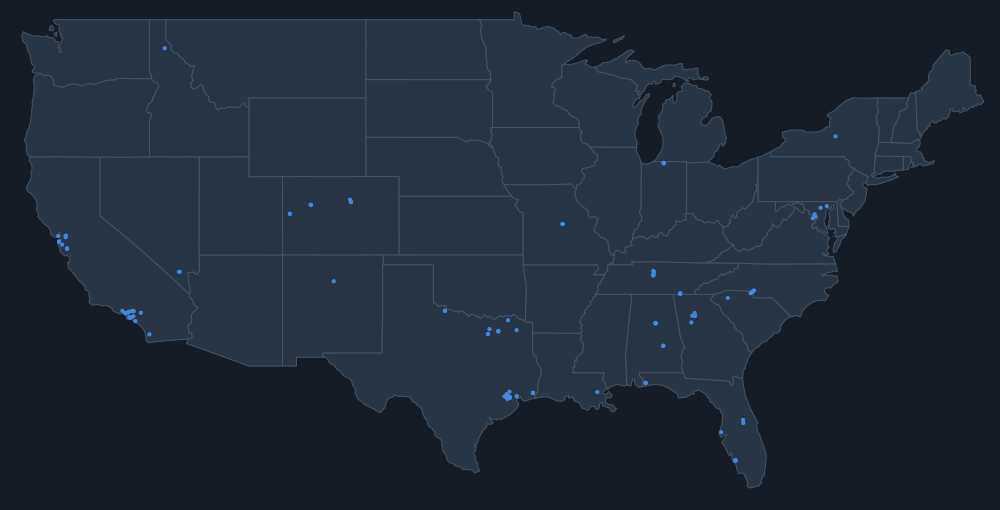
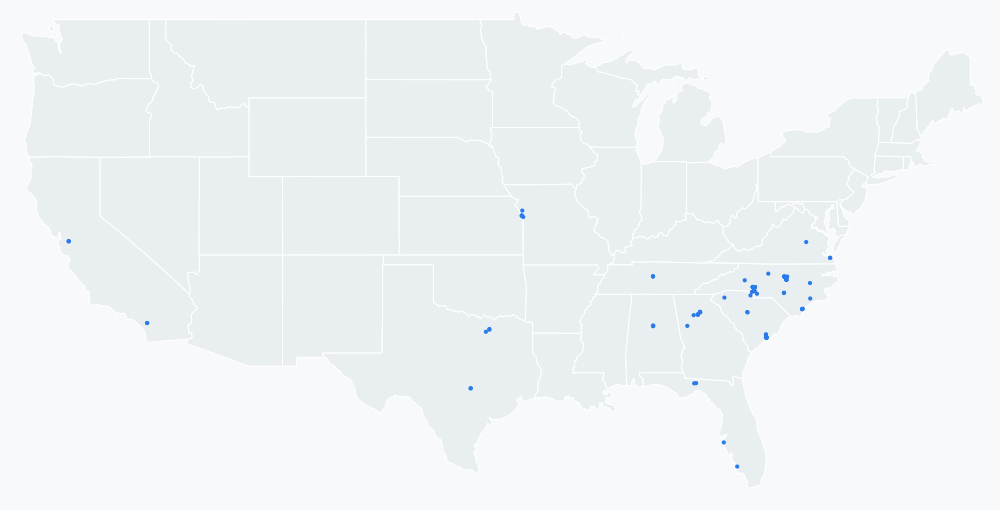
Rick Hendrick's dealership story began with a struggling Chevrolet store in Bennettsville, South Carolina, in 1976. He was 26. Fifty years later, the company he built reaches from the Carolinas to California. The Hendrick name is familiar to racing fans, but its retail business has a substantial footprint of its own. This map shows how far it has grown from that first South Carolina dealership.

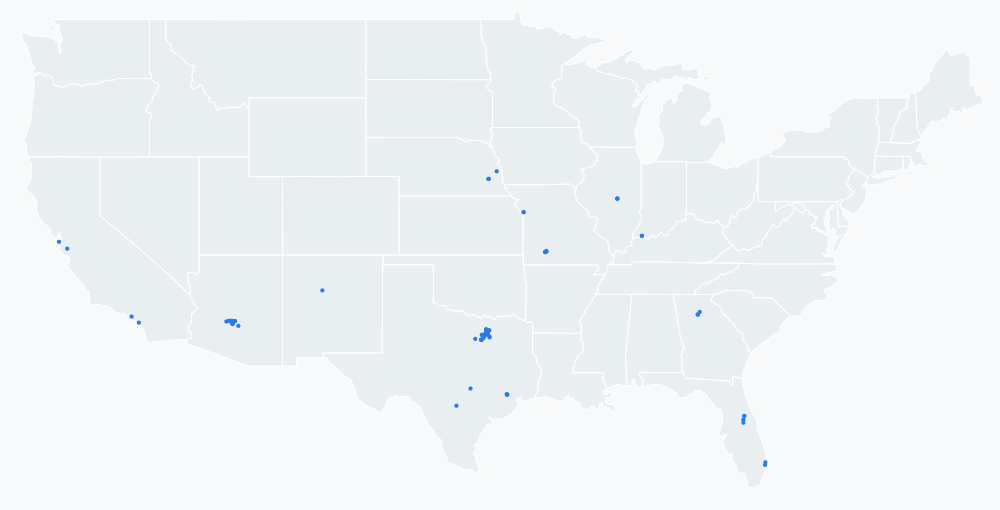
Berkshire Hathaway entered dealership retail by buying an entire group. Its 2015 acquisition of Van Tuyl created Berkshire Hathaway Automotive, adding a major dealership business to the conglomerate. The network spans ten states on this map, including Texas, Arizona, and California. It is a reminder that a local dealership can sit inside a corporate family with businesses far beyond automotive.
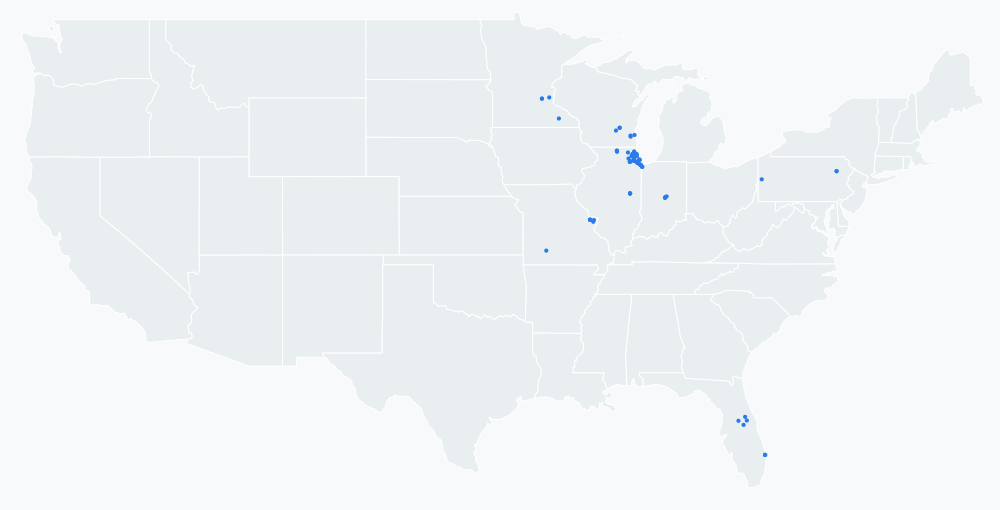
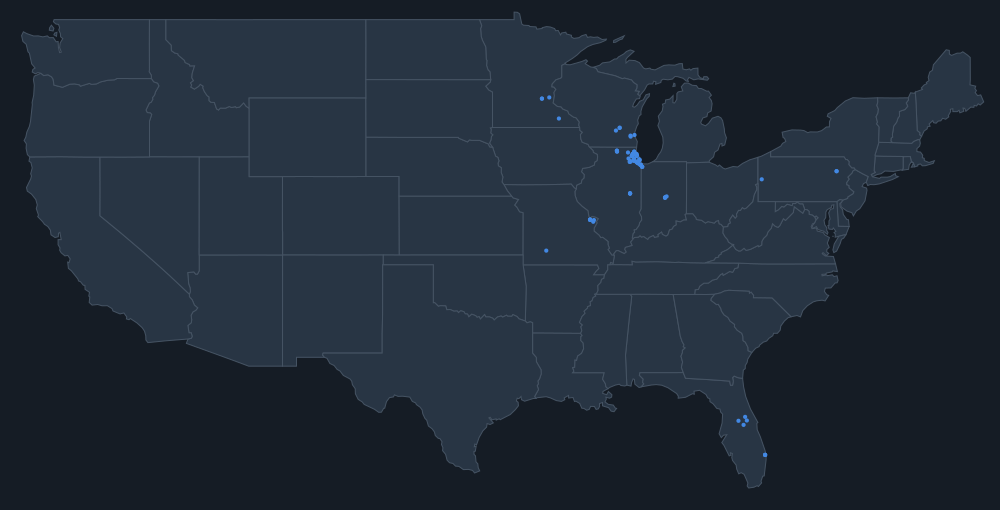
The Napleton story reaches back to a small automotive business on Chicago's South Side in 1931. What began as a family operation grew into a dealership group with a footprint well beyond Illinois. Its locations on this map span seven states, from the Midwest to Florida and Pennsylvania. The family name connects a much larger retail business than any one dealership suggests.
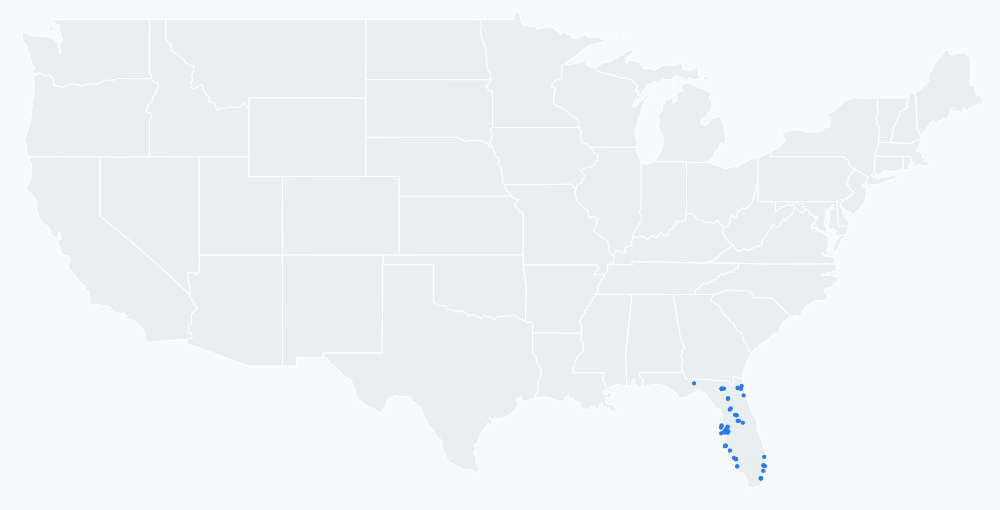
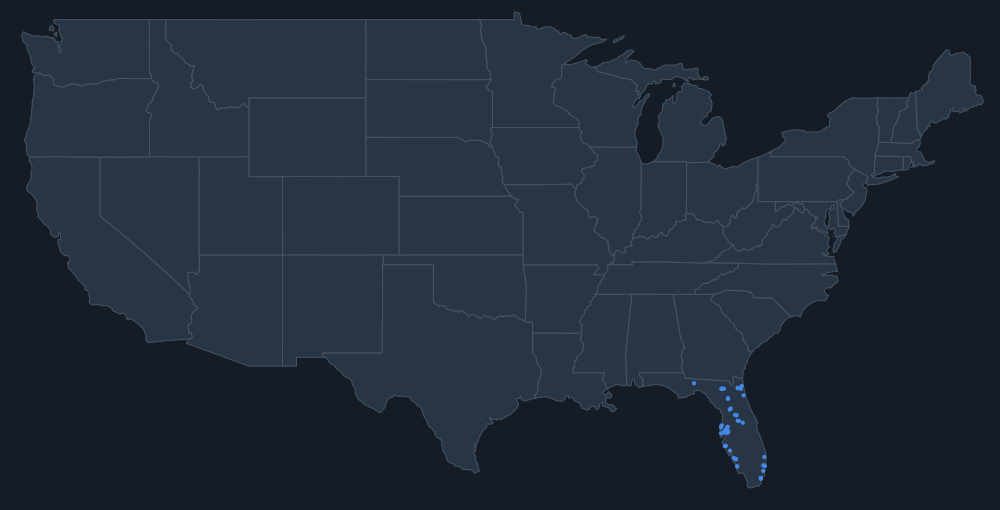
Morgan shows how much scale a dealer group can build in one state. Every dealership mapped here is in Florida, making its footprint more concentrated than the national networks above. Founder Larry Morgan came to dealerships after building the Tires Plus business. He and his son Brett bought Toyota of Tampa Bay in 2005, helping establish the foundation for the group that followed.
The six public dealer groups below reported these full-year 2025 revenues, rounded to the nearest $0.1 billion. These are company-wide reported totals, including international operations or other businesses where applicable. They are not U.S.-only franchise dealership revenue and do not determine the rooftop order above. This is a comparison of these six public groups, not a complete ranking of private and public retailers.
| Dealer group | NYSE ticker | 2025 reported revenue | Source |
|---|---|---|---|
| Lithia & Driveway | LAD | $37.6 billion | 2025 results |
| Penske Automotive Group | PAG | $31.8 billion | 2025 results |
| AutoNation | AN | $27.6 billion | 2025 results |
| Group 1 Automotive | GPI | $22.6 billion | 2025 results |
| Asbury Automotive Group | ABG | $18.0 billion | 2025 annual report |
| Sonic Automotive | SAH | $15.2 billion | 2025 results |
Lithia, AutoNation, Asbury, Group 1, Penske, and Sonic are publicly traded automotive retailers with annual SEC filings. Those filings make it possible to compare reported revenue for a common financial year. Hendrick, Ed Napleton, and Morgan are privately held groups. Berkshire Hathaway Automotive is a dealership business within Berkshire Hathaway. This article does not assign estimated revenue to private groups or assume that every subsidiary has a separately reported, comparable revenue figure. Public ownership and dealership footprint are different measures; neither alone tells you which operator performs best.
The American automotive retail landscape has changed as dealership groups acquire established regional businesses. That can expand a parent company’s footprint while familiar local dealership names remain on the buildings. Asbury is a useful example: it completed its acquisition of Larry H. Miller Dealerships in December 2021 and acquired the Herb Chambers businesses in July 2025. Larry H. Miller should therefore not be treated as a separate, independently owned group in a current parent-company ranking. Acquisitions also explain why a company’s latest reported store count can differ from a dated location dataset. The maps here follow the source’s group labels; subsidiaries are not manually rolled into parent groups. Read the methodology before comparing these rooftop counts with a company’s own total.
Large dealership groups need to connect the same core workflows: vehicle inventory, sales and CRM, finance and insurance, service, accounting, and reporting. A wider footprint makes shared data and consistent processes an important consideration when comparing dealership technology. Those requirements do not prove that every store uses the same DMS, CRM, website provider, or digital retailing tool. Acquisition history and existing contracts can leave a group with multiple systems. Verify a specific group’s current deployment through company disclosures or a dated customer announcement before treating a vendor relationship as group-wide.
For an independent dealer, the maps provide context about the groups operating in a local market. Use the footprint alongside the company profiles to understand which parent businesses sit behind familiar dealership names. When comparing technology or marketing services, focus on your own requirements: integrations, ownership of customer data, implementation effort, service support, and the needs of each location. A platform used by a large group is a research lead, not proof that it fits a single-store dealership. For acquisition research, separate the parent company, dealership brand, franchise, and physical address. That avoids counting several franchises at one site as several rooftops or listing an acquired business as an independent competitor.
Browse individual company profiles and explore other dealer groups.
Explore Dealer group directoryContinue researching technology relationships across dealer groups.
Explore Dealer group tech stacksCompare dealership management systems and operational tools.
Explore DMS platformsResearch tools for customer relationships and sales follow-up.
Explore Sales and CRMIt depends on the measure. Lithia & Driveway ranks first in this observed U.S. franchise-rooftop dataset, with 290 distinct addresses. It also reports the highest 2025 company-wide revenue among the six public retailers compared here. Those measures are different from U.S. new-vehicle unit sales and do not establish a universal ranking across every retailer.
The six public automotive retailers compared here are Lithia & Driveway (NYSE: LAD), Penske Automotive Group (PAG), AutoNation (AN), Group 1 Automotive (GPI), Asbury Automotive Group (ABG), and Sonic Automotive (SAH). Berkshire Hathaway Automotive is a subsidiary of Berkshire Hathaway rather than a separately listed dealership company.
Some sources count franchises, while others count physical locations. Company totals can include international stores, used-car operations, commercial vehicles, or other businesses. This dataset counts distinct active U.S. franchise dealership street addresses within each source-assigned group and uses a July 9, 2026 source update.
Asbury completed its acquisition of Larry H. Miller Dealerships in December 2021. The dealership name can still appear locally, but it should not be ranked as an independently owned parent group alongside Asbury.
No. A dealer group can own many dealerships across several brands and states. A ranking of dealer groups does not identify the largest individual Toyota, Ford, or other single-brand dealership by sales.
The maps show locations captured in the stated source dataset, not a live company-owned register. Later acquisitions, source coverage gaps, and group-assignment differences can affect the counts. Check company disclosures for its latest reported footprint.
Counts and maps use MarketCheck U.S. location records last updated July 9, 2026, retrieved October 15, 2026. This ranking covers active franchise dealerships assigned to a named group in those records. It does not include independent used-car stores, collision centers, or international locations. A rooftop means one distinct street address within a group. Multiple franchises sharing that address count once. Group ownership follows the source’s labels; subsidiaries are not manually reassigned. Coverage gaps and later acquisitions can affect the order, so these figures may differ from companies’ reported totals. All counted locations have map coordinates. Alaska and Hawaii appear separately where applicable. Company histories and brand information come from official company sources; our group profiles provide further reading.
Company announcement confirming completion on December 17, 2021.
Explore Asbury: Larry H. Miller acquisitionReports the Herb Chambers acquisition completed on July 21, 2025.
Explore Asbury: 2025 annual report The Automotive Playbook — The Creative Department Exclusively for Hyundai Dealerships.